A UM or UIM claim can put you in an unexpected position with your own insurance company. Even though the coverage is part of your policy, the carrier may still investigate fault, damages, causation, and the value of the claim before paying benefits.
That can mean requests for a recorded statement, medical authorizations, supporting records, and other documentation.
In some cases, the insurer may dispute whether the other driver was uninsured or underinsured, question the extent of your injuries, or challenge the amount of compensation owed under the policy.
A San Antonio uninsured motorist lawyer exists because that reversal catches most people off guard, and the wrong first move quietly costs the claim thousands.
Our team at NMW Law Firm works these first-party cases across Bexar County and the I-35 corridor. If you have not signed anything yet, call (210) 265-6565 before you do.
About NMW Law Firm and Our San Antonio UM UIM Practice
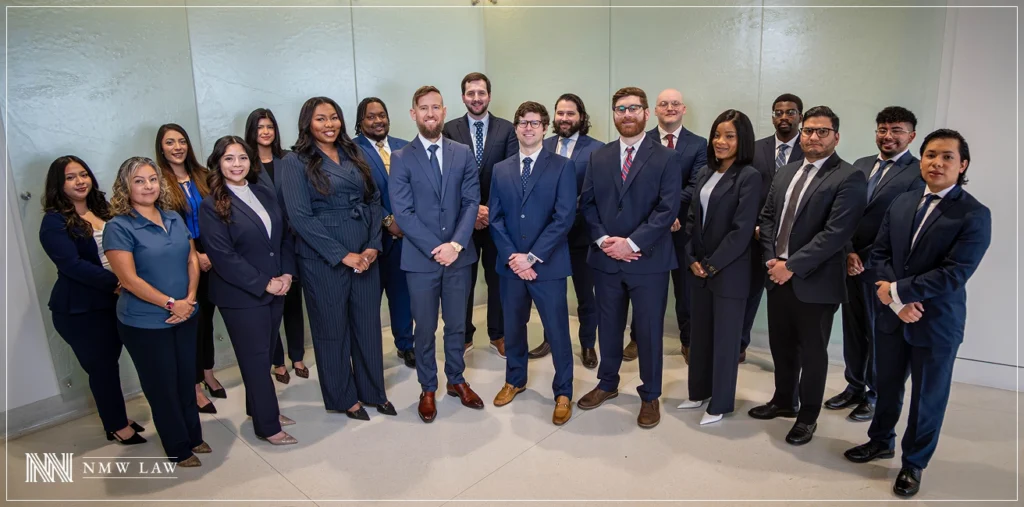
NMW Law Firm is a Texas personal injury firm with offices in Houston, El Paso, Plano, and San Antonio, and we handle uninsured and underinsured motorist claims as a regular part of our auto injury practice.
Our San Antonio personal injury attorneys work these first-party disputes because they require a different discipline than a standard liability case. Managing Partner Nicholas M. Wills leads the firm's auto and catastrophic injury work, and the team includes attorneys David G. Ghably and Keith N. Bakker.
Our approach to UM UIM cases starts with the policy itself. We pull the declarations page, we read every endorsement, and we identify every provision that may affect coverage.
We treat every carrier communication as part of the litigation record, because in a serious injury case, the file often moves toward suit. That is not the story adjusters like to tell about first-party claims, but it is the story most experienced UM UIM lawyers recognize.
We also handle related San Antonio auto matters, including San Antonio hit-and-run claims, rideshare crashes, and catastrophic injury cases. Our office is located at 711 Navarro St., Ste. 300-130, in the Travis Park Plaza building downtown.
The Legal Framework Behind Every Texas UM UIM Claim
Every UIM claim in Texas is shaped by the Texas Supreme Court's decision in Brainard v. Trinity Universal Insurance Co., 216 S.W.3d 809 (Tex. 2006).
Brainard held that a UIM carrier has no contractual duty to pay benefits until the insured establishes the uninsured or underinsured driver's legal liability and the amount of damages suffered.
The rule was reaffirmed in In re State Farm Mutual Automobile Insurance Co., 629 S.W.3d 866 (Tex. 2020) (also referred to as Irwin).
The practical effect of this rule is simple. Filing a UM or UIM claim does not automatically require the insurance company to pay.
The insured must first prove the other driver’s fault and the amount of damages. Because of that, a demand letter alone may not be enough to resolve a serious UIM claim.
What That Framework Changes About Strategy
The Brainard rule affects how a UIM claim should be prepared from the start. Medical records, crash reports, witness statements, and other proof may all be needed to show who was at fault and how much harm the crash caused.
Because these claims can turn into lawsuits, the file should be built with that possibility in mind. A San Antonio UM UIM lawyer can help organize the evidence and address disputes before they become harder to resolve.
When UM UIM Coverage May Apply After a San Antonio Crash
Texas requires every auto insurer to offer UM UIM coverage under Texas Insurance Code Section 1952.101, and the coverage is included on the policy unless the driver rejected it in writing. That coverage may be triggered in more scenarios than most drivers realize.
The following are situations where UM UIM coverage often comes into play:
- A hit-and-run on I-35 or 410 where the fleeing driver is never identified and the unknown vehicle made physical contact with the insured, the insured’s vehicle, or the vehicle the insured occupied
- A crash caused by a driver operating without any valid Texas auto policy.
- A serious injury wreck where the at-fault driver carried only 30/60/25 minimum limits under Texas Transportation Code Section 601.072.
- A multi-vehicle pileup on 1604 where the at-fault driver's coverage is quickly exhausted.
- A wreck involving a driver whose policy had lapsed before the incident.
The common thread across these San Antonio car accident scenarios is coverage failure on the other side of the crash. When the at-fault driver has nothing, has too little, or cannot be identified, the injured driver's own policy may be the source that responds.
How UM and UIM Coverage Differ Under Texas Law
UM coverage and UIM coverage share a policy home but respond to different problems. UM coverage applies when the other driver has no liability insurance or cannot be identified.
UIM coverage applies when the other driver has some liability coverage, but not enough to cover the injured driver's damages.
| Feature | Uninsured Motorist (UM) | Underinsured Motorist (UIM) |
| Trigger | No liability coverage or unidentified driver. | Liability coverage exists but is insufficient. |
| Common San Antonio example | Unidentified hit-and-run on I-35. | Serious 1604 crash with a minimum-limits driver. |
| Proof required | Fault plus damages under Brainard. | Fault plus damages plus exhaustion of the at-fault limits. |
| Governing framework | Policy language plus Chapter 1952 of the Insurance Code. | Brainard proof requirement plus policy language. |
| Common carrier posture | Corroboration disputes. | Causation and value disputes. |
The at-fault carrier's role also differs between the two coverages. In a UIM matter, that carrier usually needs to tender or exhaust its policy limits before the injured driver's own carrier fully engages, which affects the sequence in which demands are made.
When the Other Driver Is Nowhere to Be Found
Hit-and-run cases are the corner of UM law where a large number of claims get denied for reasons that were preventable.
The scenario is not unusual in South Texas, given cross-jurisdictional traffic through Bexar County and the volume of vehicles passing through downtown, the medical center, and Loop 1604.
What is less common is a claim file that meets every corroboration requirement the carrier is going to demand.
What Texas Carriers Typically Look For
Texas hit-and-run UM claims involve specific proof requirements. When the at-fault driver is unidentified, Texas law generally requires actual physical contact between the unknown vehicle and the insured person, the insured vehicle, or the vehicle the insured occupied.
A prompt police report and supporting evidence such as dashcam footage, photographs, or witness statements may also help document how the crash occurred and support the claim.
Missing any of these opens the door to a denial or a coverage dispute.
Where People Lose the Claim Without Realizing It
A driver who leaves the scene to go straight to the emergency room and files the police report the next morning may find the carrier questioning whether the incident happened as described.
A driver who chats casually with the adjuster before hiring counsel may inadvertently create the record the carrier later uses to deny the claim. These are avoidable outcomes when the sequence gets handled correctly.
The Carrier's Playbook in a First-Party Claim
Adjusters handling UM UIM claims work from a well-established set of practices. Recognizing those practices is part of not walking into them.
The following patterns are commonly reported in Texas UM UIM matters:
- The adjuster requests a recorded statement before the injured driver has retained counsel.
- The carrier requests duplicate medical records multiple times to extend the timeline.
- The carrier raises causation disputes tied to any prior injury or prior treatment.
- The carrier argues that policy notice provisions were not satisfied.
- The carrier makes an early low offer designed to close the file cheaply.
None of these tactics are illegal, and all of them are strategic. When a carrier crosses the line into unreasonable delay or denial, the insured may have separate claims under Texas Insurance Code Chapter 541 for unfair claim settlement practices.
Before giving a statement to your own adjuster, have a lawyer review the policy. Call (210) 265-6565.
Multiple Policies and Multiple Coverages: What Texas Actually Allows
The question of whether a UM UIM claimant may combine, or stack, limits across multiple vehicles or policies is a common source of confusion in Texas.
Texas law does not provide a general right to stack UM UIM limits simply because a household has multiple vehicles or multiple policies.
Under Texas Insurance Code Section 1952.104, an auto policy may include provisions that limit UM UIM recovery regardless of the number of vehicles or policies involved, and Texas Supreme Court authority has enforced anti-stacking language within multi-vehicle policies.
How the Question Actually Gets Answered
The availability of additional UM UIM coverage in a given case depends on how each policy is written, not on a broad rule of stacking. Some policies contain clear anti-stacking language that limits recovery to a single vehicle's UM UIM limit.
Others contain language that may permit recovery under more than one policy in specific circumstances. Umbrella policies and separate policies held by different household members present their own coverage analysis.
Why Every Policy Deserves a Careful Read
A UM UIM claim attorney in San Antonio typically starts by pulling every policy that may apply to the insured or the vehicle involved, including any umbrella policy.
That review may uncover additional coverage or confirm that recovery is limited to a single policy. Either way, it gives the client a clearer picture of the coverage available.
Damages Recoverable Under Texas UM UIM Coverage
A UM UIM claim in Texas recovers the same categories of damages the injured driver could pursue against the at-fault driver, subject to the applicable policy limits.
Those categories include past and future medical expenses, lost income and reduced earning capacity, physical pain and mental anguish, physical impairment, and, in wrongful death cases, the categories provided under the Texas Wrongful Death Act.
Policy limits set the ceiling on any UM UIM recovery, which is why the coverage analysis matters so much. A claim that appears capped against a $25,000 UM limit may look different once the full coverage picture is understood.
No lawyer may promise a specific outcome, and coverage analysis is fact-specific in every case.
Deadlines That Apply to a UM UIM Case in Texas
Two different kinds of deadlines matter in a UM UIM case, and they are not the same thing. The underlying tort claim, which is the claim against the at-fault driver's conduct, is generally governed by the two-year personal injury limitations period in Texas Civil Practice and Remedies Code Section 16.003.
The contractual claim against the insurer for UM UIM benefits is subject to its own accrual analysis under Texas case law, which may depend on when the carrier denies the claim or when specific facts trigger accrual.
The policy itself also imposes deadlines. Most policies require prompt notice of the claim, and missing the notice deadline may create coverage arguments the statute of limitations never would.
The takeaway on deadlines is that waiting is rarely helpful. Adjusters gain room to argue causation as time passes, medical gaps become defenses, and prior conditions become explanations.
Getting a lawyer involved early keeps the timing questions from becoming reasons for denial.
FAQs for San Antonio Uninsured Motorist Lawyer
Do I have to sue my own insurance company to get UIM benefits?
Often yes, filing suit against your own insurance company is sometimes required to recover UIM benefits in Texas. Under Brainard, a UIM carrier has no obligation to pay until the insured establishes the other driver's liability and the amount of damages.
Carriers rarely agree to the value of a serious case without litigation being on the table.
Will filing a UM UIM claim raise my insurance rates?
Filing a UM UIM claim does not automatically mean your insurance rates will increase. Texas insurers may consider several factors when setting premiums, including your claims history, driving record, location, and the insurer’s own rating rules.
A not-at-fault UM UIM claim may affect rates differently depending on the carrier and the circumstances, so it is best to ask your insurer how the claim could affect your policy.
What happens if I already gave a recorded statement to my insurance company?
It depends on what you said. Giving a recorded statement to your carrier is not automatically fatal to a UM UIM claim, though it may create disputes about causation or fault later in the process.
A lawyer may request a copy of the statement and structure the rest of the file with any concerns from that statement in mind.
Can my UM UIM coverage pay if I was a passenger in someone else's car?
Generally yes, UM UIM coverage on your own policy may pay when you are injured as a passenger in another vehicle, subject to policy terms.
Texas UM UIM coverage often follows the insured person, not just the insured vehicle. A review of the declarations page confirms how the coverage is written.
Does UM UIM cover pedestrian and bicycle crashes with uninsured drivers?
Yes, UM UIM coverage on your own auto policy may extend to pedestrian and bicycle injuries caused by an uninsured or hit-and-run driver, depending on the policy language. Texas law often treats the coverage as protecting the insured person in circumstances beyond driving the covered vehicle.
Past Case Results
Read the Policy Before the Carrier Reads You
The declarations page contains answers most drivers never think to look for until it is too late. Policy language, coverage limits, and any umbrella endorsements all shape what a claim may become. Every one of those details may change the direction of the case.
Have a San Antonio uninsured motorist lawyer at NMW Law Firm walk through your policy before the next call with the adjuster. Bring the crash report, the declarations page, and any paperwork the carrier has already sent over.
Call (210) 265-6565 or visit our office at 711 Navarro St., Ste. 300-130, Travis Park Plaza in downtown San Antonio.